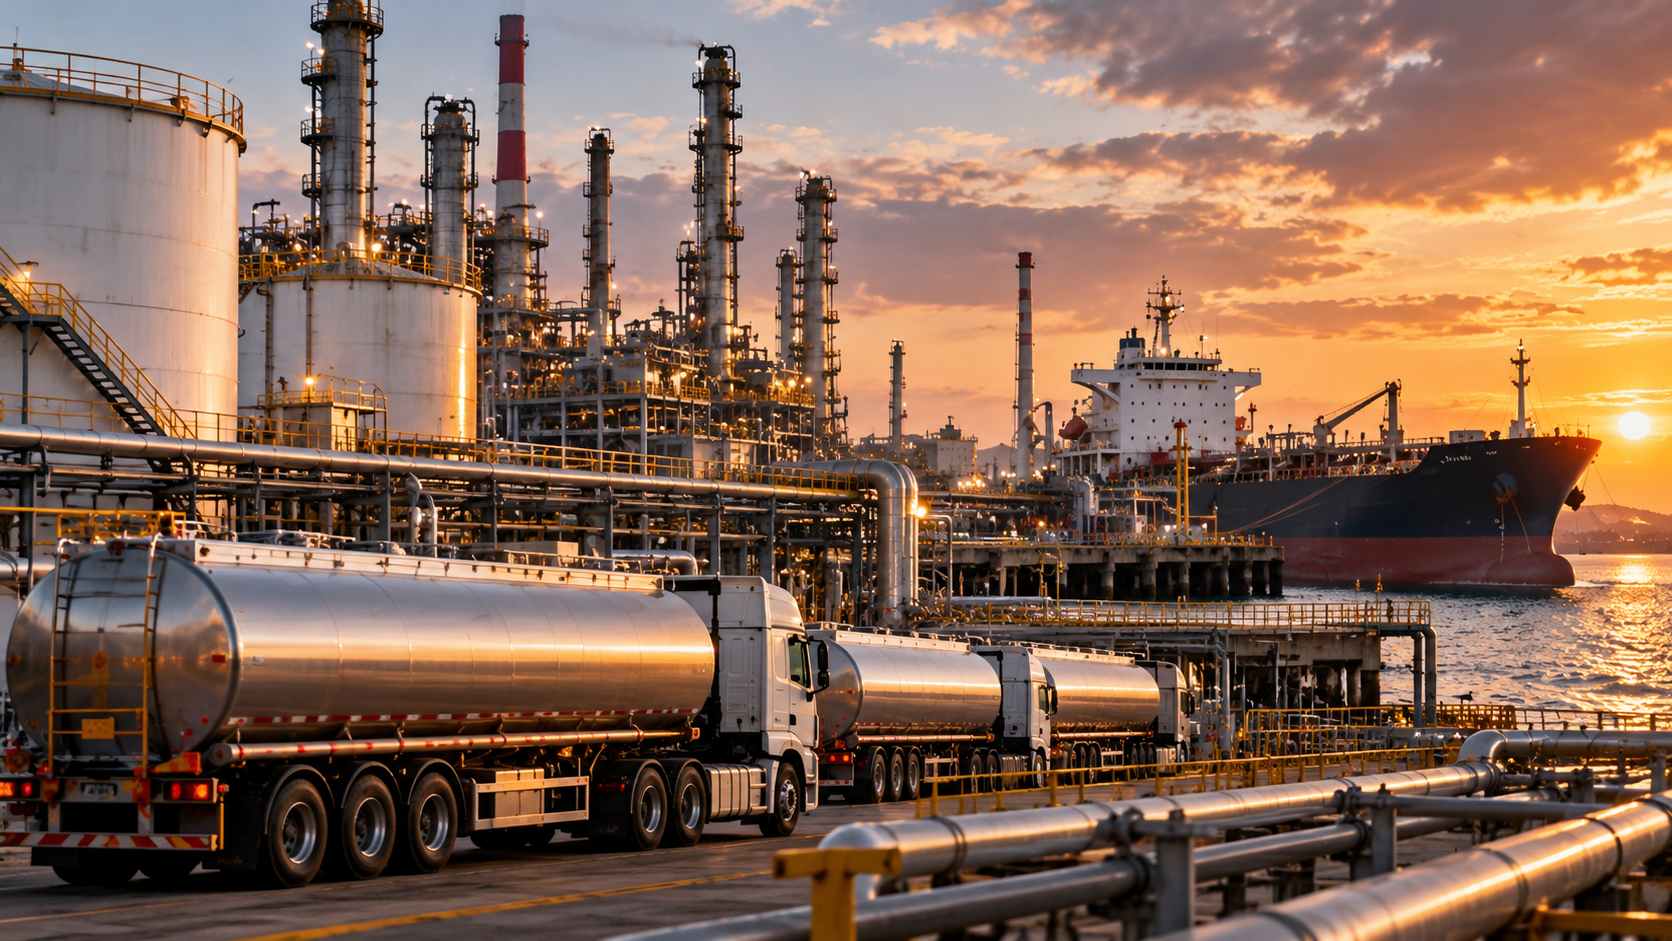
Russia is set to supply up to 4.8 million tonnes of diesel under a temporary US licence, a move that could ease some pressure in global fuel markets even as refinery and supply constraints remain.
Washington/Moscow, October 10 — A major diesel supply arrangement between the US and Russia could bring up to 4.8 million tonnes of fuel into the global market, offering some relief at a time when diesel supplies remain tight.
According to reports, Russia will initially supply more than 300,000 tonnes of diesel, followed by another 500,000 tonnes in November. A further 1 million tonnes is expected later, with an additional 3 million tonnes to follow depending on the operating condition of Russian refineries.
The supply arrangement comes under a temporary US Treasury licence that will allow Russian diesel to reach global buyers until April 2027. The move is significant because it opens the door for additional Russian fuel flows into international markets at a time when diesel prices have remained elevated.
Global diesel markets have been under pressure due to supply disruptions and geopolitical tensions, particularly around the Strait of Hormuz. Higher freight risks and concerns over supply availability have already pushed diesel prices sharply upward in recent months.
Even so, the new Russian supply may not fully resolve the shortage. Monthly supply of around 3 million tonnes would still amount to less than one million barrels a day, while demand in major consuming markets remains much higher.
The actual impact on markets will depend on whether the promised volumes are delivered on time. Refinery outages, shipping constraints, insurance issues and payment arrangements could all affect the flow of diesel cargoes.
The development may also have implications for India. Indian refiners are major exporters of petroleum products, and broader access to Russian diesel in global markets could increase competition and influence export margins.
Overall, the deal could help cool some of the recent tightness in diesel markets, but it is unlikely to eliminate supply concerns entirely unless deliveries remain steady and broader geopolitical risks ease.