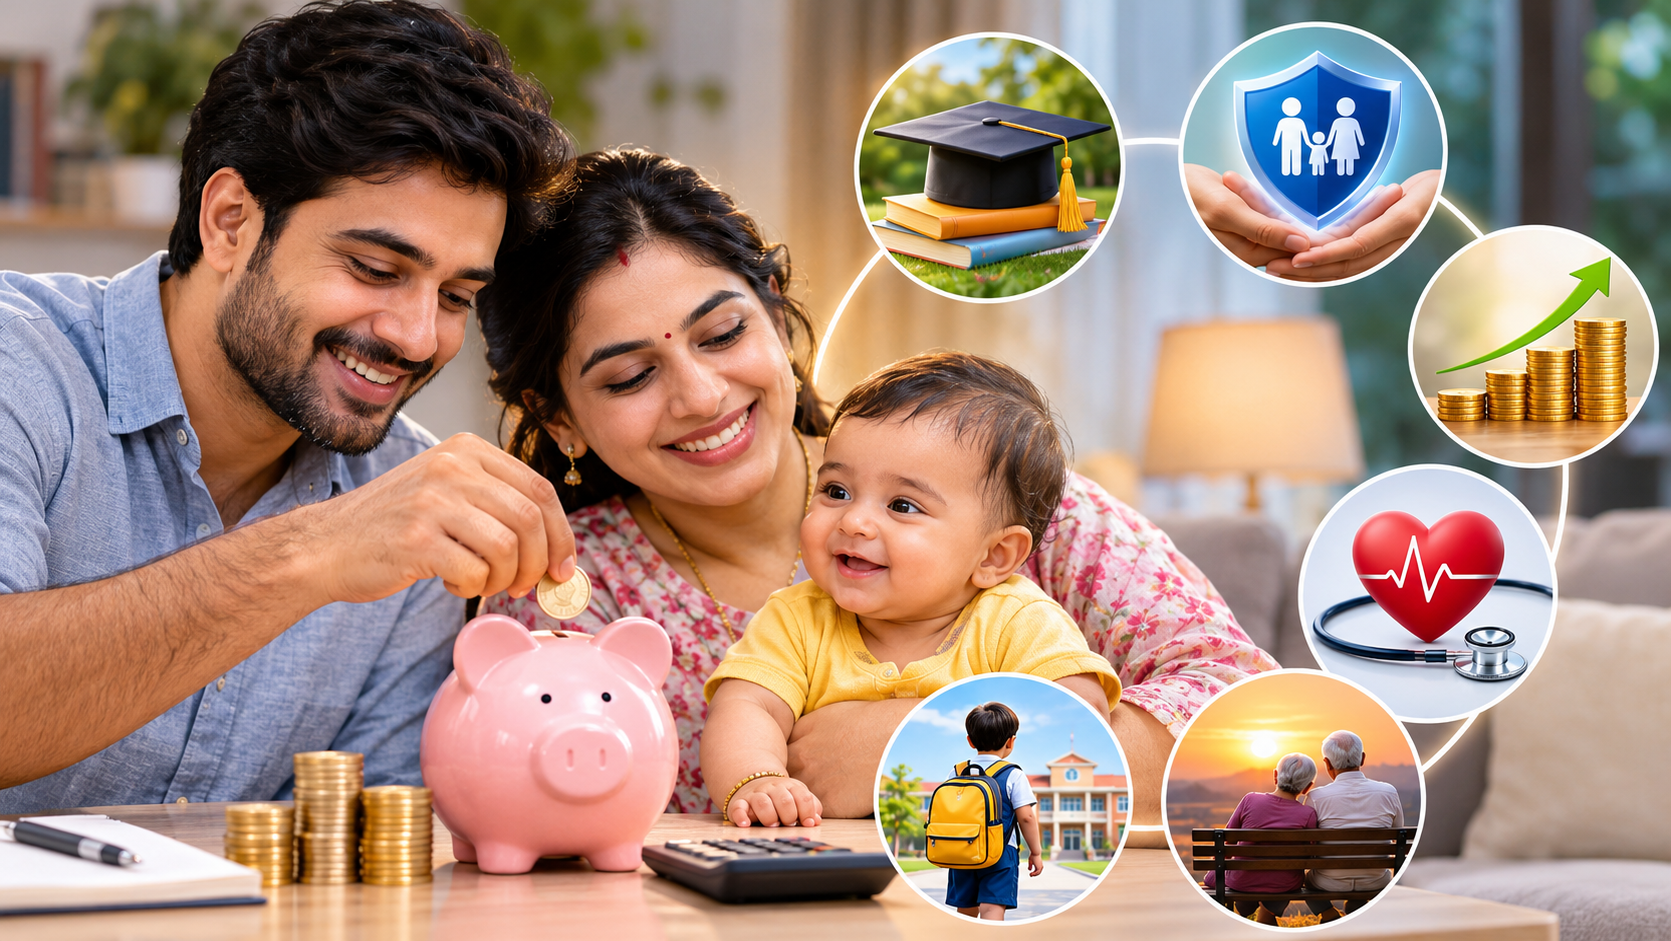
Raising a child involves more than meeting everyday expenses. From building an education fund and buying insurance to securing retirement, early planning can help parents prepare for their child’s future without putting their own finances at risk.
Highlights
- Start financial planning as soon as your child is born.
- Build an emergency fund covering at least six months of expenses.
- Begin a monthly SIP to create a long-term education corpus.
- Secure adequate term life and family health insurance.
- Account for rising education costs and inflation.
- Focus on children’s health, skills and emotional development.
- Balance your child’s future needs with your retirement savings.
Becoming Parents? 7 Important Steps to Secure Your Child’s Future Financially and Emotionally
Becoming a parent is one of life’s biggest milestones, bringing happiness, responsibility and new financial challenges. From healthcare and schooling to higher education and everyday expenses, raising a child requires long-term planning.
Financial experts generally recommend starting early rather than waiting until education expenses become significant. Even small monthly investments can grow into a substantial corpus over time, while insurance and emergency savings can provide protection against unexpected financial difficulties.
Here are seven important steps new parents should consider.
1. Build an Emergency Fund
The first priority should be financial stability. Parents should maintain an emergency fund covering at least six months of essential household expenses.
This fund can help manage unexpected medical bills, job losses or other financial emergencies without disturbing investments intended for the child’s future.
2. Start a Monthly SIP for Education
Higher education can become one of the biggest expenses for parents. Starting a Systematic Investment Plan (SIP) early allows families to benefit from long-term compounding.
For example, investing ₹5,000 every month for 18 years could grow to approximately ₹30 lakh, assuming an annualised return of 10%.
The total investment would be ₹10.80 lakh, while the remaining amount would represent potential investment gains. However, mutual fund returns are market-linked and not guaranteed.
3. Buy Term and Health Insurance
Insurance should form an essential part of family financial planning.
A term life insurance policy can provide financial support to dependants if an earning parent dies unexpectedly.
Similarly, comprehensive family health insurance can help protect savings against rising medical expenses. Parents should also check that their newborn is included in the policy.
4. Plan for Rising Education Costs
Education expenses are likely to increase over time, making inflation an important factor in financial planning.
For instance, a college programme costing ₹10 lakh today could cost approximately ₹28.5 lakh after 18 years if education costs increase by 6% annually.
Parents should therefore estimate future education expenses rather than planning solely around today’s fees.
5. Focus on Health and Skill Development
A child’s future depends on more than financial resources.
Parents should prioritise vaccinations, proper nutrition, physical activity and regular developmental assessments.
As children grow, investing time in communication, problem-solving, creativity and digital literacy can help prepare them for changing career opportunities.
6. Teach Financial Discipline Early
Introducing money management during childhood can help develop responsible financial habits.
Parents can begin with simple concepts such as saving pocket money, distinguishing needs from wants and setting small financial goals.
As children mature, they can gradually learn about budgeting, banking, investments and responsible digital transactions.
7. Don’t Ignore Retirement Planning
While securing a child’s future is important, parents should not compromise their own retirement savings.
Depending entirely on children for financial support during retirement can create additional pressure on the family.
Maintaining separate investments for retirement and children’s education can help achieve both objectives.
Why Early Planning Matters
Starting early provides parents with more time to save, invest and adjust their financial strategies.
A well-structured plan should combine emergency savings, adequate insurance, long-term investments and consistent attention to children’s emotional and educational needs.
The objective is not simply to accumulate wealth but to create a secure environment where children can develop confidence, pursue opportunities and become financially independent.