Highlights:
- New return-correction mechanism proposed from the April 2027 return period.
GSTR-3B liability would align with GSTR-1, GSTR-1A and IFF disclosures. - ITC reporting would align with GSTR-2B, with separate tracking for specified credits.
Invoice Management System would receive formal recognition under GST rules. - Wider recommendations include easing blocked-credit restrictions and expanding refunds.
- Public consultation is open on MyGov until November 30, 2026.
Businesses could face a major change in how they correct GST returns from April 2027, under a proposed mechanism designed to reduce mismatches in tax liability and input tax credit (ITC).
Recommended by the GST Council at its 57th meeting on October 8, 2026, the framework centres on correcting errors in the underlying records rather than making independent adjustments in the summary return, GSTR-3B. The changes remain proposals, subject to finalisation and the required legal amendments.
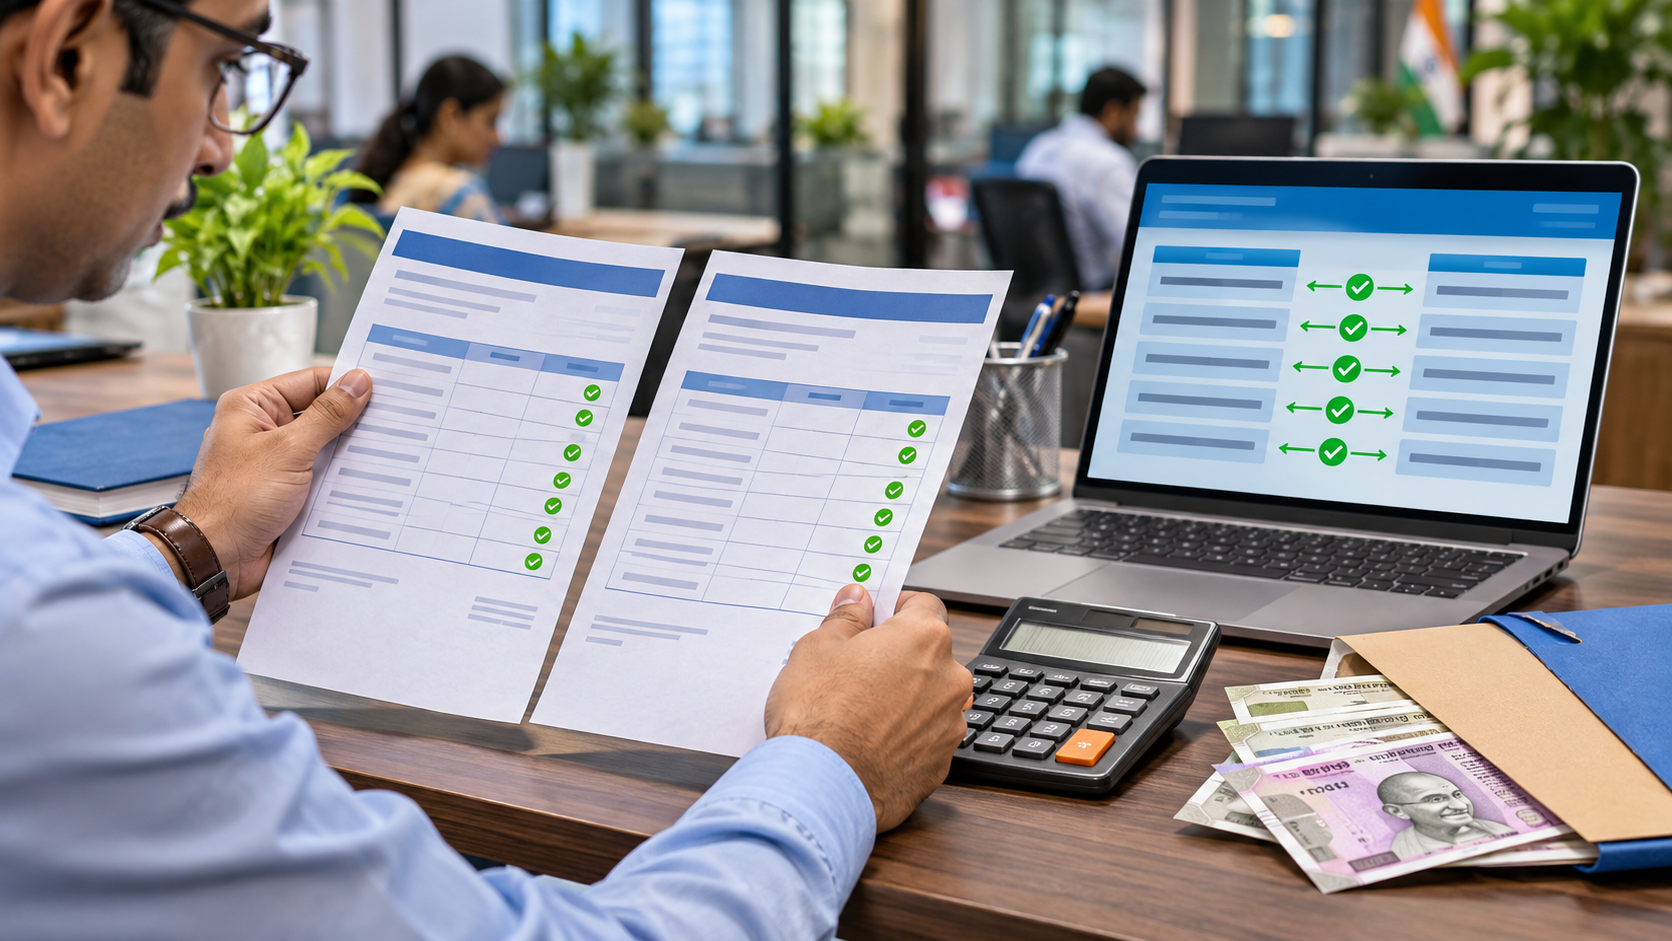
Under proposed Rule 61(1A), liability reported in GSTR-3B would align with outward supplies declared in GSTR-1, GSTR-1A or the Invoice Furnishing Facility. Sales-reporting errors would therefore need correction through the relevant outward-supply mechanism.
Proposed Rule 61(1B) would similarly align ITC claimed in GSTR-3B with credit available in GSTR-2B, with separate treatment for reverse-charge and reclaimed credit.
The package would also give formal recognition to the Invoice Management System through proposed Rule 60(6A). Buyers would be able to accept, reject or keep supplier documents pending, subject to prescribed conditions. Separate electronic statements would track credit reversals and reclaims, and reverse-charge tax payments and corresponding credit claims. Changes to DRC-03 would capture underlying invoice details for payments.
The broader recommendations include easing blocked-credit restrictions on outdoor catering, health and life insurance, telecom towers, pipelines outside factories, free samples and certain legally required disposals of expired goods. The Council has also proposed wider accumulated-credit refunds and an opportunity to challenge the blocking of credit ledgers. These benefits would depend on the relevant amendments taking effect.
While tighter alignment could reduce routine mismatch notices, implementation will require careful drafting. Linking credit more closely to supplier-reported information increases the importance of timely supplier compliance and accurate invoice reconciliation.
The final framework will also need clarity on correction deadlines, rejected credit notes, quarterly filers and differences carried forward into the new system. Reducing procedural mismatches would not, by itself, resolve every dispute over eligibility for credit.
Businesses can prepare by identifying manual adjustments currently made in GSTR-3B and checking how each would be handled under the proposed framework. Regular invoice reconciliation, follow-up with suppliers and accounting-software updates would help teams adapt.
Public comments on the proposed mechanism are invited through MyGov until November 30, 2026, giving businesses and tax professionals an opportunity to flag practical difficulties before the rules are finalised.